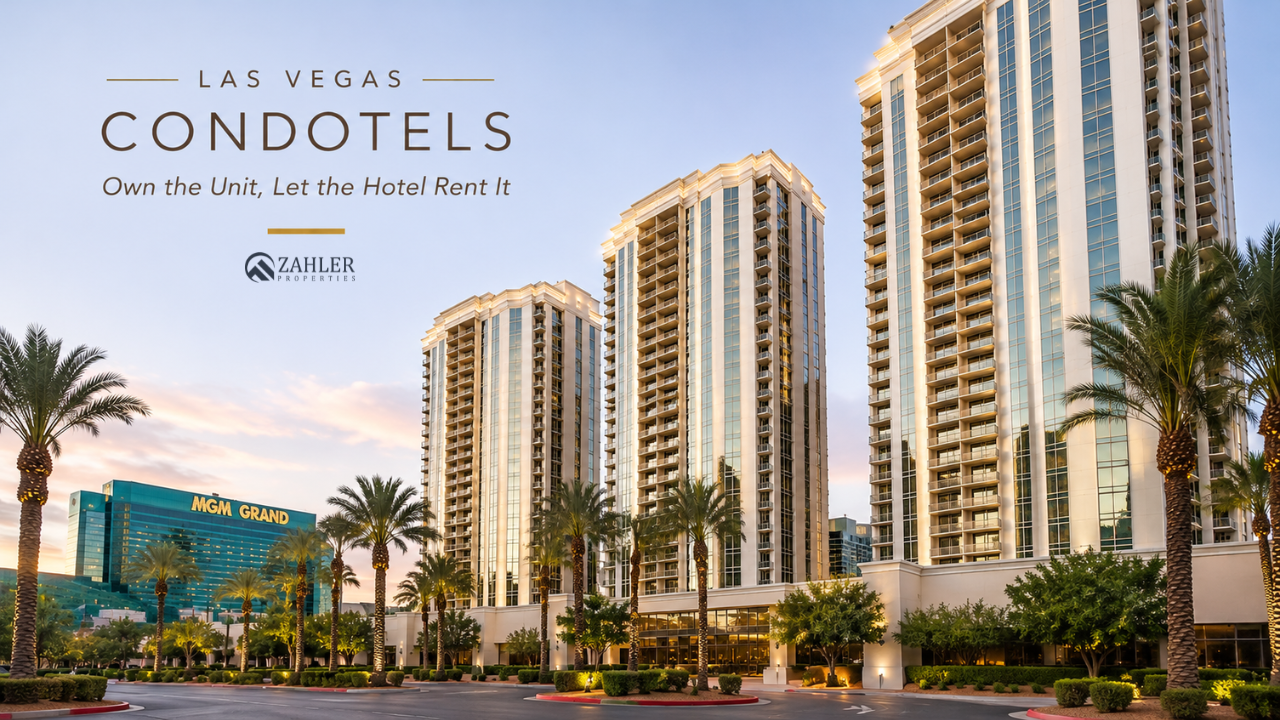
Can you buy a hotel room on the Las Vegas Strip, use it when you are in town, and let the hotel rent it out the rest of the year? Yes. That is what a condotel (condo-hotel) is. The part most people miss is everything that comes with it: a different kind of loan, a rental program you do not control, and a smaller pool of buyers when you sell.
Here is how the structure works, where the costs sit, and what to check before you write an offer.
What a condotel actually is
A condotel unit is an individually deeded unit inside a building that operates as a hotel. You get a recorded deed and a parcel number like any condo owner. Unlike a timeshare, you own a specific physical unit, not a slice of usage time.
The difference is what surrounds the unit. Instead of a residential building, you are inside a working hotel with a front desk, housekeeping and nightly guests. When you are not using the unit, you can typically place it in the hotel’s rental program. The operator markets it, books it, cleans it, and splits the room revenue with you.
Las Vegas has one of the deepest condotel markets around. Local brokerage guides list buildings such as Vdara, The Signature at MGM Grand, Palms Place, Trump International, The Platinum and the Waldorf Astoria residences among the towers on or near the Strip that carry this kind of ownership. Each building has its own declaration, rental agreement and owner-use rules, and they are not interchangeable.
How the hotel rental program works
- You enroll the unit. In most Las Vegas condotels, participation is optional rather than required, but the terms are set by the operator.
- The hotel rents it as a room. The operator sets nightly rates, chooses guests and handles check-in, cleaning and maintenance.
- Revenue is split. The operator keeps a share of gross room revenue and passes the rest to you, often after fees such as credit card processing, marketing or cleaning. One Las Vegas brokerage guide puts the operator’s share at roughly 40 to 50 percent of gross room revenue. Treat that as a rough range and get the actual split from the building’s rental agreement.
- Your use is scheduled around the program. Owner stays are usually booked through the hotel, and some buildings limit how many nights owners can use or when.
The tradeoff is control. You do not set the rate on a big convention weekend and you do not pick your guests. You are a passive participant in a professionally run program.
Why most lenders will not finance a condotel
This is where most deals get decided. Fannie Mae’s Selling Guide lists projects that are managed and operated as a hotel or motel as ineligible, even when the units are individually owned. Its criteria include an HOA licensed as a hotel or resort, rental pooling arrangements, revenue or profit sharing with a hotel rental company, hotel-type services such as registration desks and daily cleaning, and projects marketed as a hotel or investment opportunity. A Strip condotel checks several of those boxes.
The practical result: a standard conventional mortgage is generally off the table. Buyers pay cash or use portfolio and non-QM lenders, which typically means a much larger down payment, a higher rate than a conventional loan, and reserve requirements. Local sources cite down payments of 25 percent or more, but terms vary widely by lender and by building, so talk to a lender who actually closes condotel loans before you shop seriously.
If you are still deciding how much cash to put into any purchase, our breakdown of 3, 5, 10 or 20 percent down in Las Vegas covers the conventional side of that decision for comparison.
What owners still pay when the unit sits empty
- Monthly dues. Condotel dues tend to run higher than a typical residential condo because they help fund hotel-level services.
- Property taxes and insurance. You carry these whether or not the unit rents.
- Furniture and finish refresh. Operators often require owners to update furniture, fixtures and equipment so units match the rest of the hotel. Ask how often and what the last assessment cost.
- Program fees. Cleaning, booking and processing charges can come out before your share is paid.
An illustration with assumed numbers
This is an illustration only, with made-up figures, to show how the math stacks up. It is not a projection for any building.
| Gross room revenue for the year (assumed) | $30,000 |
| Operator share at 45 percent (assumed) | minus $13,500 |
| Owner share | $16,500 |
| Monthly dues of $800 x 12 (assumed) | minus $9,600 |
| Taxes and insurance (assumed) | minus $2,500 |
| Left before any refresh assessment, financing or vacancy swings | $4,400 |
Change the occupancy, the split or the dues and that bottom line moves fast. Add a loan payment and it can go negative. That is why I look at a condotel as a place you will use that can offset some of its costs, not as a cash-flow rental.
The securities angle most buyers never hear about
Back in 1973, the SEC issued guidance (Release No. 33-5347) on when selling a condo unit together with a rental arrangement can become the sale of a security. Features it flagged include pooled rental income and offers that emphasize investment returns. It is one reason many hotel rental programs are structured as optional and why their marketing is careful about income promises. For a buyer, the takeaway is simple: read exactly what the rental agreement says, and do not rely on anyone’s verbal income estimate.
Resale: your buyer faces the same limits you did
When you sell, your buyer runs into the same financing problem, which shrinks the pool of people who can purchase your unit. Fewer qualified buyers can mean a longer time on the market and less pricing power. Plan your exit with that in mind rather than assuming a condotel will move like a conventional condo in Summerlin or anywhere else in the valley that a buyer can finance with a standard loan.
Before you buy a Las Vegas condotel, check these
- The recorded declaration and the rental program agreement. Is the program optional? Can you rent the unit yourself? What are the owner-use limits?
- Real operating numbers. Ask for recent owner statements, average occupancy, the actual split and every fee deducted before payout.
- Dues history and reserves. How have dues changed, and when was the last furniture or finish assessment?
- Financing first. Get terms from a portfolio or non-QM lender before you fall for a unit.
- Livability. Many units have limited kitchens and no dedicated resident amenities. Make sure it fits how you will actually use it.
- Exit math. Price your eventual sale assuming the next buyer needs cash or a specialty loan.
Tax treatment of rental income, depreciation and personal-use days can get complicated with a condotel. Confirm the specifics with your CPA, an attorney for the documents, and your lender for financing.
If you are coming from out of state and this would be your Las Vegas base, our guide to buying a Las Vegas home from out of state covers the remote side of the process.
Source: Fannie Mae Selling Guide B4-2.1-03, Ineligible Projects; SEC Release No. 33-5347 (1973), Guidelines as to the Applicability of the Federal Securities Laws to Offers and Sales of Condominiums or Units in a Real Estate Development; Nevada Real Estate Group, Las Vegas Condo Hotels guide; IRES, Can You Rent Out a Condo-Hotel Unit in Las Vegas. Information is accurate as of the date of this post and can change.
Geoff Zahler | Broker/Owner, Zahler Properties